Showing posts with label closing costs. Show all posts

Friday, May 24, 2019

The Impact Staging Your Home Has On Your Sale Price


Some Highlights:

  • The National Association of Realtors surveyed their members & released the findings of their Profile of Home Staging.
  • 62% of seller’s agents say that staging a home decreases the amount of time a home spends on the market.
  • 50% of staged homes saw a 1-10% increase in dollar-value offers from buyers.
  • 77% of buyer’s agents said staging made it easier for buyers to visualize the home as their own.
  • The top rooms to stage in order to attract more buyers are the living room, master bedroom, kitchen, and dining room.

Thursday, May 23, 2019

2019 Colors of the Year


It’s that fun time of the year where us paint color geeks look forward to the paint manufacturers announcing their annual “Colors of the Year”.  Most of the manufacturers have announced their colors in the last couple of weeks and today I’m excited to share the 2019 Colors of the Year with you from Sherwin Williams, BEHR, Ace’s Clark + Kensington, PPG and Dutch Boy.

Wednesday, May 22, 2019

Boomerang Buyers: Don’t Be Afraid to Buy a Home Again!


According to CoreLogic, from 2006 to 2014 “there were 7.3 million housing foreclosures and 1.9 million short sales.” The hesitation some Americans feel after experiencing a foreclosure brings to mind the old saying: “Fool me once- shame on you. Fool me twice- shame on me.”

According to the 2019 Home Buyer Report from NerdWallet,
“Thirteen percent of Americans have lost a home due to a financial event such as foreclosure in the past 10 years. More than 6 in 10 of them (61%) have not bought a home since, and 20% of those who haven’t repurchased say they never plan to again.”
This makes sense. They don’t want to go through the same pain again. As a cornerstone of the American dream, nobody wants to lose homeownership. But let’s illustrate this simply: Recall learning to ride your first bike during your childhood. Did you stop riding it because you fell on the ground and scraped your knees? Or did you get back on and try again until you were able to ride without falling?

Purchasing a home is not as simple as learning to ride a bike, but the concept is the same! There are many things necessary to learn that affect the ability to get the financing needed to purchase a home. Past occurrences can determine if there is a waiting period. In other words, you need to let your knees heal before you try again!
As we’ve mentioned in the past, homeownership has many financial and non-financial benefits. Each person needs to go over the pros and cons, taking the time to figure out what is best for their family. Should they continue renting, or should they try to buy again?

The good news is that some “boomerang buyers” are getting back into the market. They’re getting back on their bike!
“Of 2.8 million former homeowners whose foreclosures, short sales or bankruptcies dropped off their credit reports from January 2016 to November 2018, 11.5% have obtained a new mortgage, according to a study by credit rating agency Experian for USA Today.”
NerdWallet’s report also mentioned:
  • 6% plan to buy a house this year.
  • 39% intend to buy over the next 3 years.
  • 58% say they will purchase within 5 years.

Bottom Line

If you lost a home due to a financial event but would like to review your options, contact a local real estate professional that can help you create a plan to obtain a home in the future!

Wednesday, February 22, 2017

Monday, February 13, 2017

3 Questions to Ask If You Want to Buy Your Dream Home

If you are debating purchasing a home right now, you are probably getting a lot of advice. Though your friends and family will have your best interest at heart, they may not be fully aware of your needs and what is currently happening in the real estate market. Ask yourself the following 3 questions to help determine if now is a good time for you to buy in today’s market.

1. Why am I buying a home in the first place?

This is truly the most important question to answer. Forget the finances for a minute. Why did you even begin to consider purchasing a home? For most, the reason has nothing to do with money. For example, a survey by Braun showed that over 75% of parents say “their child’s education is an important part of the search for a new home.” This survey supports a study by the Joint Center for Housing Studies at Harvard University which revealed that the top four reasons Americans buy a home have nothing to do with money. They are:
  • A good place to raise children and for them to get a good education
  • A place where you and your family feel safe
  • More space for you and your family
  • Control of that space
What does owning a home mean to you? What non-financial benefits will you and your family gain from owning a home? The answer to that question should be the biggest reason you decide to purchase or not.

2. Where are home values headed?

According to the latest Existing Home Sales Report from the National Association of Realtors (NAR), the median price of homes sold in December (the latest data available) was $232,200, up 4.0% from last year. This increase also marks the 58th consecutive month with year-over-year gains. If we look at the numbers year over year, CoreLogic forecasted a rise by 4.7% from December 2016 to December 2017. On a home that costs $250,000 today, that same home will cost you an additional $11,750 if you wait until next year.

What does that mean to you?

Simply put, with prices increasing each month, it might cost you more if you wait until next year to buy. Your down payment will also need to be higher in order to account for the higher price of the home you wish to buy.

3. Where are mortgage interest rates headed?

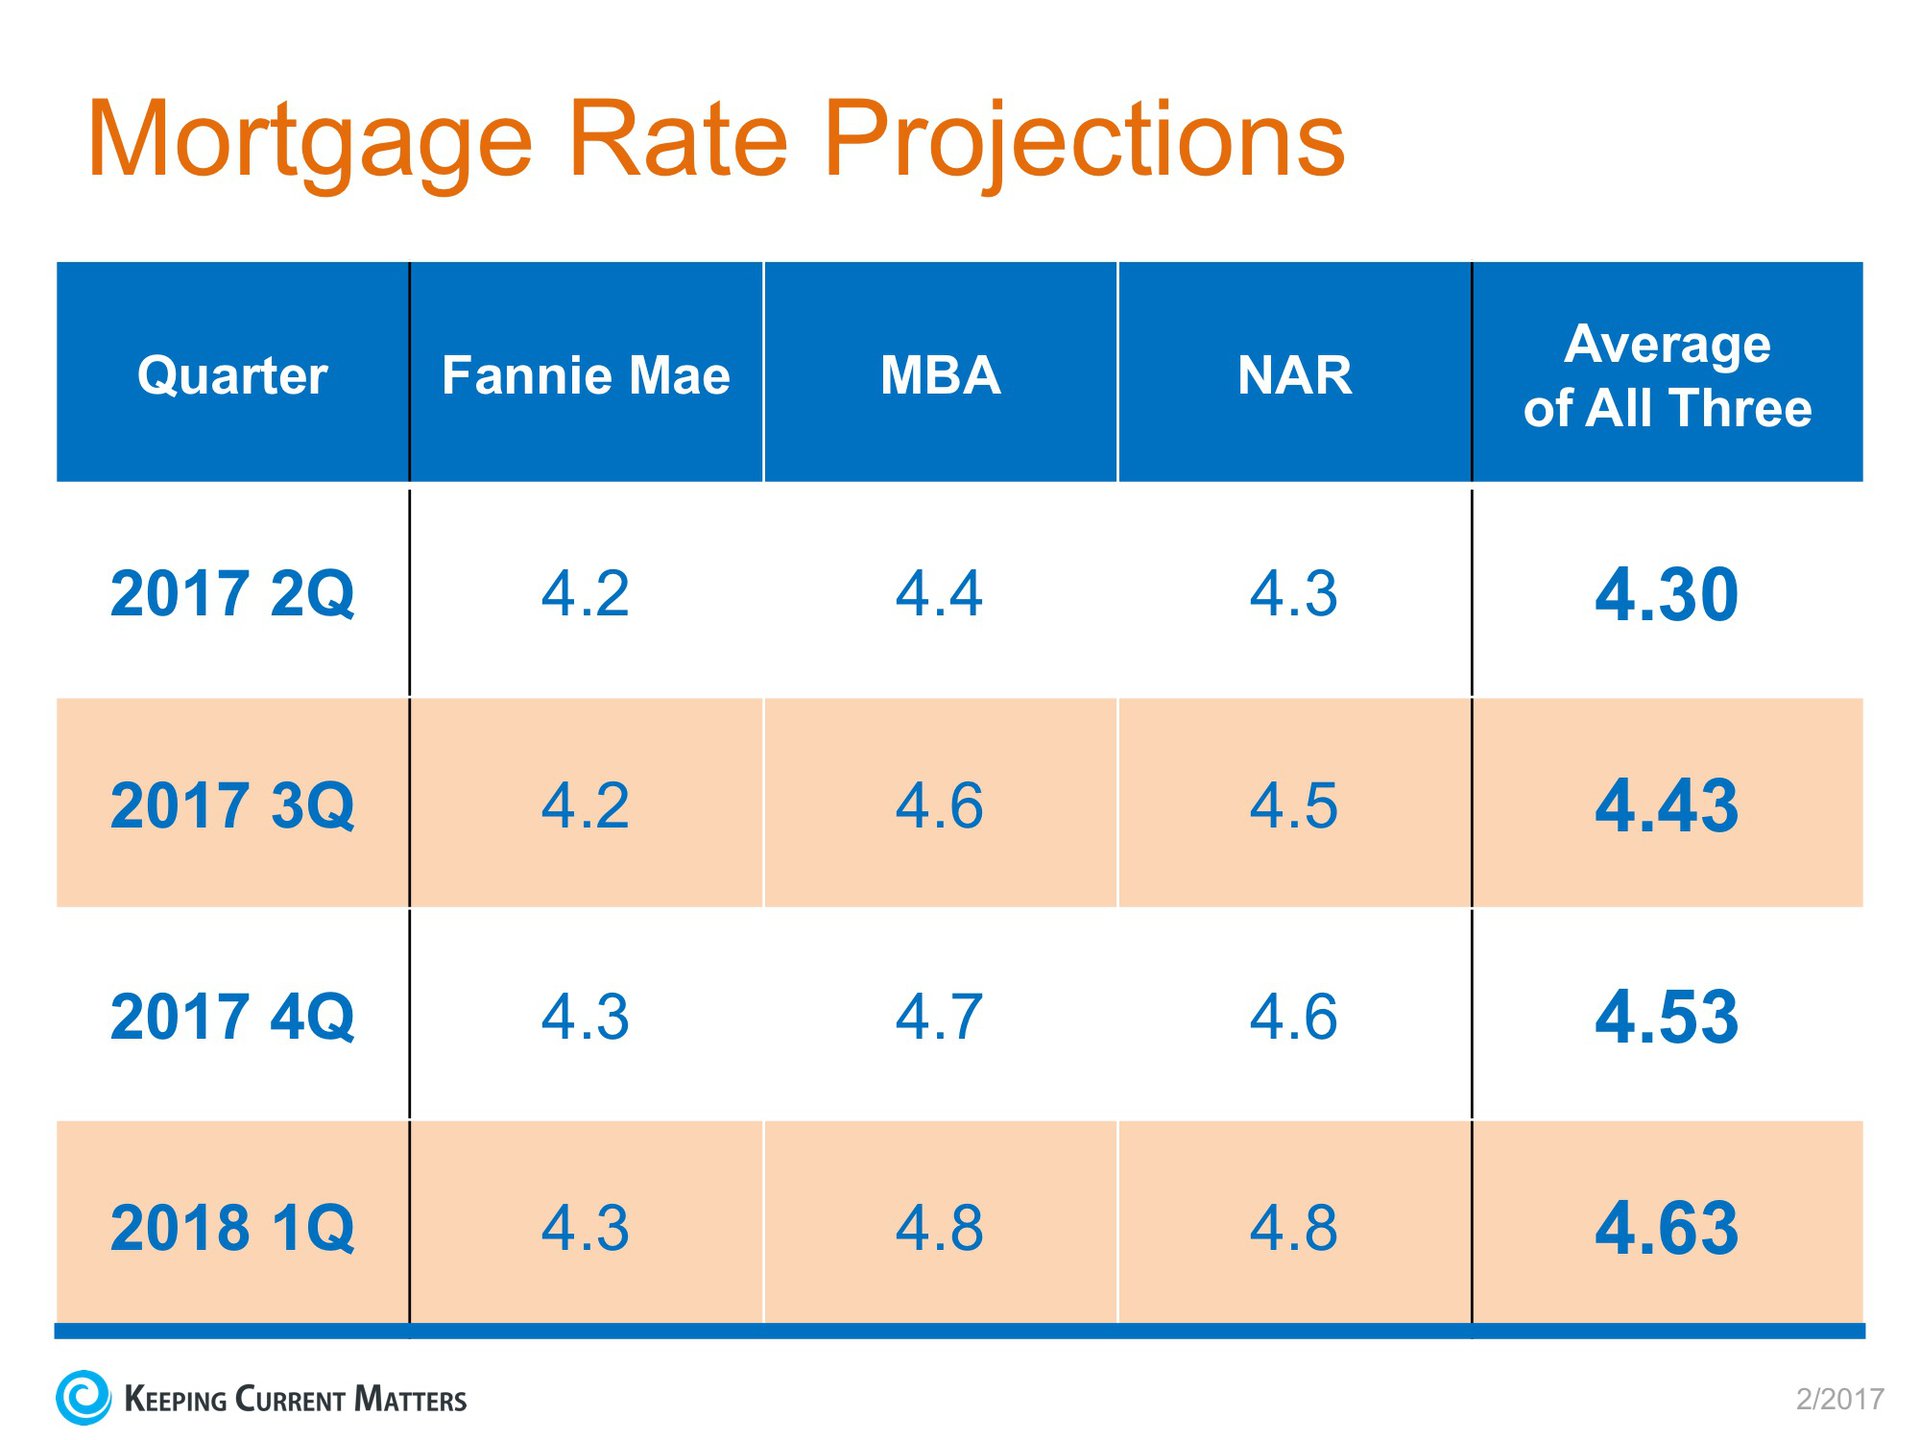
A buyer must be concerned about more than just prices. The ‘long-term cost’ of a home can be dramatically impacted by even a small increase in mortgage rates. The Mortgage Bankers Association (MBA), the National Association of Realtors, and Fannie Mae have all projected that mortgage interest rates will increase over the next twelve months, as you can see in the chart below: 3 Questions to Ask If You Want to Buy Your Dream Home | Keeping Current Matters

Bottom Line

Only you and your family will know for certain if now is the right time to purchase a home. Answering these questions will help you make that decision.

Tuesday, January 31, 2017

Lower Property Taxes

The most likely case for lower property taxes is that you bought your house at a time when the economy was doing much better. At that time, you would have paid more for your home than it would be valued at now. Because of the higher price tag, you naturally paid more in taxes. Lowering your property taxes isn’t a particularly difficult process, but it is a process nonetheless. And with upfront expenses like a potential assessment of your property, it may be a case of “you need money to save money.” But if the market was more inflated at the time of your home purchase than it is now, lowering your property tax will be beneficial in the long run!


Monday, January 23, 2017

Have You Saved Enough for Closing Costs?


There are many potential homebuyers, and even sellers, who believe that they need at least a 20% down payment in order to buy a home or move on to their next home. Time after time, we have dispelled this myth by showing that many loan programs allow you to put down as little as 3% (or 0% with a VA loan). If you have saved up your down payment and are ready to start your home search, one other piece of the puzzle is to make sure that you have saved enough for your closing costs. Freddie Mac defines closing costs as: 
“Closing costs, also called settlement fees, will need to be paid when you obtain a mortgage. These are fees charged by people representing your purchase, including your lender, real estate agent, and other third parties involved in the transaction. Closing costs are typically between 2 and 5% of your purchase price.”
  • We’ve recently heard from many first-time homebuyers that they wished that someone had let them know that closing costs could be so high. If you think about it, with a low down payment program, your closing costs could equal the amount that you saved for your down payment. Here is a list of just some of the fees/costs that may be included in your closing costs, depending on where the home you wish to purchase is located:Government recording costs
  • Appraisal fees
  • Credit report fees
  • Lender origination fees
  • Title services (insurance, search fees)
  • Tax service fees
  • Survey fees
  • Attorney fees
  • Underwriting fees

Is there any way to avoid paying closing costs?

Work with your lender and real estate agent to see if there are any ways to decrease or defer your closing costs. There are no-closing mortgages available, but they end up costing you more in the end with a higher interest rate, or by wrapping the closing costs into the total cost of the mortgage (meaning you’ll end up paying interest on your closing costs). Home buyers can also negotiate with the seller over who pays these fees. Sometimes the seller will agree to assume the buyer’s closing fees to get the deal finalized, which is known in the industry as ‘seller’s concession.’

Bottom Line
Speak with your lender and agent early and often to determine how much you’ll be responsible for at closing. Finding out you’ll need to come up with thousands of dollars right before closing is not a surprise anyone is ever looking forward to.